
Four Major Impacts of the Recent Bank Collapses on the Multifamily Housing Sector
The collapses of institutions such as Silicon Valley Bank and Signature Bank are rippling through the multifamily housing market. This article outlines four key impacts, including regional bank stress, development financing difficulties, CMBS volatility, and interest rate uncertainty, and cites observations from multiple industry executives.
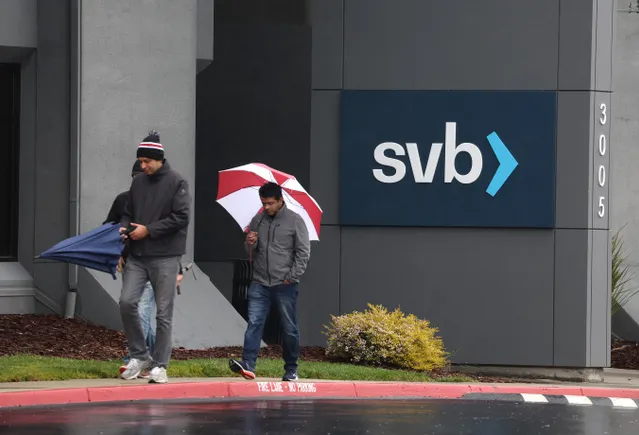
Recently, the collapse of institutions such as Silicon Valley Bank and Signature Bank shook the commercial and real estate lending sectors. The multifamily housing industry was not immune to this turmoil. Signature Bank was the third-largest lender for apartment loans in New York City; and according to Bloomberg, Silicon Valley Bank, in addition to funding real estate technology startups, also injected over $2 billion into affordable housing investments.
Even apartment executives with no business ties to these banks are closely monitoring developments. "We just went through the failure of two banks," said Tim Peterson, Chief Investment Officer at The Altman Cos., a developer, builder, and management company based in Fort Lauderdale, Florida. "There are isolated issues of balance sheet management and business focus behind these events, and you could say 'this isn't something that happens to everyone.' But you absolutely have to stay vigilant."
As the dust settles, the full impact of this banking crisis on the apartment market is not yet entirely clear, and may only become apparent over a longer period. However, lenders and borrowers in this sector have identified four key points worth watching.
Regional Banks Under Pressure
While seeking to build 10,000 units of affordable housing, Eddie Lorin planned to start a project in Las Vegas. But the founder and CEO of Alliant Strategic Development suddenly faced financing difficulties. "One of our lenders told me that after what just happened, there is absolutely no way they will fund a $100 million construction loan this year," Lorin said. "They were originally going to be the land lender and naturally become our construction lender."
Now, Lorin has to wait for market volatility to subside before seeking alternative funding sources. But many observers believe it could be quite difficult to find smaller banks willing to lend. "I think the smaller banks that were providing financing for a large volume of real estate transactions will have less capital available," said Ross Pemmerl, Chief Credit Officer at UC Funds, a debt provider specializing in bridge loans.
"The golden era where every deal could get financed on the most aggressive terms is over."
— Tim Peterson, Chief Investment Officer, The Altman Cos.
Following the collapse of Silicon Valley Bank and Signature Bank, rating agencies such as Moody's have warned of potential problems at smaller banks. As regulatory and political scrutiny intensifies on small and mid-sized banks, Lorin believes more banks will retreat from the apartment market.
Others share similar views. "Regional banks provided significant liquidity support to the apartment industry, especially in New York, where Signature Bank provided $4.4 billion in multifamily loans last year," said Michael J. Hurley Jr., Managing Partner at New York law firm Cassin & Cassin LLP. "Therefore, I think you will see regional banks pull back somewhat in lending to the multifamily sector."
Concerns Over Development Financing
Any slowdown at smaller banks could affect all apartment executives, but as Lorin's example shows, developers may bear the brunt. "I think the slowdown is more in construction loans and value-add renovation capital," Pemmerl said.
Peterson noted that even if smaller banks are still issuing construction loans, they won't be overly aggressive in the current environment. He mentioned that a lender recently told him the bank had already issued enough loans in 2021 and 2022 to achieve its required return, so there was no need to be as aggressive in 2023.
"Approximately $25 billion in multifamily securitized loans will mature in 2023."
— Michael Hurley, Managing Partner, Cassin & Cassin LLP
"The golden era where every deal could get financed on the most aggressive terms is over," Peterson said. "We are returning to an era of traditional underwriting and banker prudence."
In the affordable housing sector, where developers need to secure financing before they can obtain tax credits, the impact of banking problems could be particularly severe. "If you are competing for tax credits, unless everything is properly arranged and locked in, you will face stricter scrutiny," Lorin said.
CMBS Market Volatility
Although the broader multifamily market did not show volatility in the days following the bank failures, the commercial mortgage-backed securities (CMBS) and collateralized loan obligation (CLO) markets experienced some turbulence. "The first quarter was one of the slowest periods for CMBS/CLO market activity, which we attribute to rising interest rates and volatility in commercial real estate valuations," Pemmerl said. "The combination of interest rates and market uncertainty led investors to demand wider spreads, which pushed up underlying spreads and squeezed returns."
The volatility in the securitization market is crucial for a wave of new lenders that have emerged over the past five years. "Beyond regional banks, there are many lenders that rely on capital markets, such as CMBS lenders," Hurley said. "Over the past five years, many significant non-traditional lenders have emerged, and quite a few have capital market strategies that involve exiting through CLOs."
"If (the bank failures) transmit to the market and potentially curb the sharp rise in interest rates, that could be positive for the commercial real estate market in the long run, and even in 2023."
— Ross Pemmerl, Chief Credit Officer, UC Funds
If the securitization market stabilizes, Hurley believes some CMBS and bridge lenders will return to the market. "I think CMBS, bridge lenders, and Fannie Mae and Freddie Mac will be able to fill some of the liquidity gap that regional banks might leave," Hurley said.
If smaller lenders fade away, this could be crucial. "Approximately $25 billion in multifamily securitized loans will mature in 2023," Hurley noted. "The market demand for financing is real. You can't push every problem down the road. You need fresh capital from borrowers, mezzanine lenders, and senior mortgage lenders."
Interest Rate Uncertainty
It is still too early to determine how the recent bank failures will affect apartment transaction volume. But according to data from MSCI Real Assets, apartment sales in January and February fell by 71% and 76% year-over-year, respectively, and it would be difficult for transaction activity to become even slower.
If anything, the problems at Silicon Valley Bank and Signature Bank could delay any rebound, said Anne Olson, CEO of Centerspace, a REIT based in Minot, South Dakota. She had initially expected the transaction market to recover in the third quarter, driven by developers being forced to sell projects. "I do think these recent failures and what has happened over the past 30 days will delay it slightly," Olson said.
Olson believes that before the sales market recovers, "people need to know where the ceiling on interest rates is, or at least roughly where it is." Many observers believe the bank failures could ultimately force the Federal Reserve to pause its rate hikes. In March, the Fed raised interest rates by 25 basis points but signaled that hikes may be nearing an end.
If that happens, many apartment executives expect transaction activity to pick up. "If (the bank failures) transmit to the market and potentially curb the sharp rise in interest rates, that could be positive for the commercial real estate market in the long run, and even in 2023," Pemmerl said.
Clickhereto subscribe and receive multifamily and apartment industry news like this in your inbox every business day.


